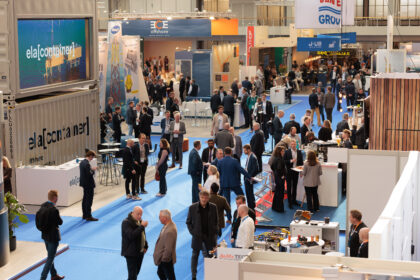

A panel at CHEM UK discuss how the industry is managing onerous regulations and geopolitical instability
Lubricants are ubiquitous across many key areas of process manufacturing – most notably in pumps, compressors, conveyors, hydraulic systems and turbines. Despite the product’s widespread use and the maturity of sector, ecosystems and supply chains within it are often complicated. Players include vendors, distributors, manufacturers, service providers and financiers and they must all comply with different regulations.
In an interesting panel debate held at the process and chemicals industry trade show CHEM UK last month, four lubricants luminaries discussed the challenges and opportunities faced by the sector.
The regulatory landscape
A big topic for lubricants manufacturers is the ever changing regulatory landscape: common revisions might include reclassification of long-standing chemicals or how, when and where chemicals can be used. Similarly legislation from different regions might stipulate different conditions complicating trade between countries. David Wright the director general of the UKLA (United Kingdom Lubricants Association) said that recent tension related to the EU and UK’s regulatory practices was an example of this. “The EU has recently said that we need the highest level of protection possible, while the UK is moving more towards a risk based exposure model, thereby ensuring the regulation is proportional. It should be remembered that the vast majority of chemicals placed on the market have been through extensive testing, a gateway process really, they are therefore very safe. The EU’s ‘absolute hazard approach’ means there is a divergence. He went on to explain that the UK’s more lenient approach could help businesses claw back some of the 10-15% in lost trade following Brexit.
Ryan Beckett international sales manager from SIP Speciality Oils And Fluids said “From our perspective as a small business, we ensure that compliance with regulation is part of our value proposition, and so relay new compliance to customers. We also believe that regulation can spark innovative practices rather than prevent them.”
Beckett went on to explain that each supply chain participant will have a different regulatory environment and that small companies don’t always have a regulations department. “We therefore rely on industry bodies like the UKLA to scan the horizon,” he said.
Wright concurred with this and said it was an essential that the organisation supported smaller players in the field. He also explained that although the regulatory landscape was complex and often difficult to manage, rules created “can actually be a catalyst for change.” By way of example, he said, “the 2023 reclassification of formaldehyde as a product with a maximum emission limit, meant many manufacturers had to upgrade their processes. The regulations have changed again, but the industry effectively reinvented itself.”
An industry experiencing change
All panel members agreed that the industry had seen huge change over the last few years. Colin Morton, an advisor and consultant to the chemicals industry said: “The sector has really shifted. Brexit encouraged companies to create local rather than global supply chains, and the ongoing Ukrainian conflict and the resulting restriction on oil had a similar effect. In addition there is a huge push to move from fossil fuels to biooils.
With complexities of this sort, there has been a growing appetite for M&A and consolidation, since larger organisations are better able to deal with increased costs that came with these advances. A recent example was the acquisition of Chem Arrow by Motul a global leader in the supply of lubricants to the HVAC market. The move strengthens Motul’s global presence in the industrial sector and underscores its ambition to become a key global player in lubricants for metal parts manufacturing.
But as Morton said there are also moves in the other direction with some companies realising that a small tailored solution may be better able to navigate the changing landscape. Examples given included Jim Ratcliff from Ineos’s acquisition of BP’s specialist business in 2021. This allowed Ineos to integrate BP’s Hull site and expand its footprint in Belgium. It also gave the smaller company access to technologies like Infinia advanced recycling technology for PET.
Agility in the supply chain
The panel spent some time talking about how companies needed to be increasingly agile with the aforementioned changes putting pressure on business models. Andrew Gelder, technical product and sales development manager for Lubricants IMCD, explained that again he thought the solution was to ‘go local rather than global’ with a focus on agility. Although larger companies are better equipped to deal with regulations, smaller companies can react more quickly to demands. Wright gave the example of Leeds-based Viccus Oils which received a call from a potential client in Sweden saying that they needed an environmentally sound lubricant for a ship’s stern. The MD was able ask his chief chemist to begin working on the product immediately and the company is now the market leader in the field. Gelder added: “A multi-national company would not be able to do this, large companies typically have multiple conversations and a complicated sign off process to before getting a new product off the ground.”
For more information visit: www.UKLA.org.uk